

The answer is rarely a round number someone heard from a friend. Family coverage needs are built from real obligations, real people, and real timelines.
Most families that ask this question already have some coverage. What they usually do not have is a clear picture of what that coverage is meant to pay for. A number that felt right when the policy was bought may not reflect today’s mortgage, childcare costs, or income.
Start by pulling together a few inputs: income, debt, dependents, existing coverage, and timeline. With those in hand, the question becomes something you can actually work through.
The largest need for many families is income replacement. If a household depends on a paycheck, the question is how many years of support would be needed if that paycheck stopped. A surviving spouse may still work, but the family may need breathing room, childcare support, debt coverage, or time to make new plans.
A simple multiple of income can be a starting point, but it should not be the end of the conversation. A 35-year-old with young children and a mortgage is in a different position than a 58-year-old with adult children and fewer debts.
Mortgage debt, student loans, business loans, credit cards, and co-signed obligations all matter. Some debts may be forgiven or handled through estate rules. Others may create immediate pressure for the family. The planning question is not only what is legally owed. It is what would create practical stress for the people left behind.

This is why a planning review should include the mortgage balance, monthly household expenses, education goals, and any obligations tied to the insured person. Life insurance is often most useful when it prevents a surviving family from having to sell assets quickly.
For parents, coverage should be measured against the child raising years. That may include childcare, school costs, activities, healthcare, and the cost of keeping the household stable. The need may decrease over time, but it rarely disappears all at once.
Planning for children also means thinking beyond a lump sum. Naming beneficiaries, choosing guardians, and deciding whether a trust is needed can be just as important as the coverage number itself.
A strong review usually looks at income, debt, dependents, savings, existing policies, employer coverage, and how long support would be needed. Resources like Life Happens Life Insurance 101 can help explain the basics, but the final answer should be personal.
The right amount is the amount that supports the actual life being protected. Too little coverage can create a false sense of security. Too much coverage may strain the budget unnecessarily. The goal is a number that is thoughtful, current, and connected to the family plan.
Use these to turn the family’s situation into numbers before you pick a coverage amount.
Is there a rule of thumb for how much life insurance a family needs?
You will often hear a multiple of annual income, such as ten times. That can be a reasonable starting point, but it ignores debt, the ages of the children, existing savings, and how long support would be needed. Treat it as a first draft, not the answer.
Does a stay-at-home parent need life insurance?
Often, yes. The household would still need childcare, transportation, and daily support if that parent were gone, and those costs are real even when they do not appear on a paycheck.
Should coverage try to cover every possible expense?
Usually not. Coverage is typically built around the obligations that would hurt most: income replacement, debt, and children’s costs. A review helps decide what to prioritize and what the budget can sustain.
If you have questions about your current coverage or want to understand how your policy fits into the broader picture, I am happy to walk through it with you. Reach out at info@kusmiderconsulting.com or call (713) 487-8855. The conversation is where it actually gets useful.
As a full-service, independent brokerage based in Houston, Texas and available throughout the U.S., we specialize in aligning insurance solutions with broader financial strategies. We provide expert guidance, unbiased product recommendations, and ongoing policy oversight to ensure your coverage evolves with your needs.
Whether you're reviewing your own protection or advising clients, we’re committed to helping you make informed, confident decisions.
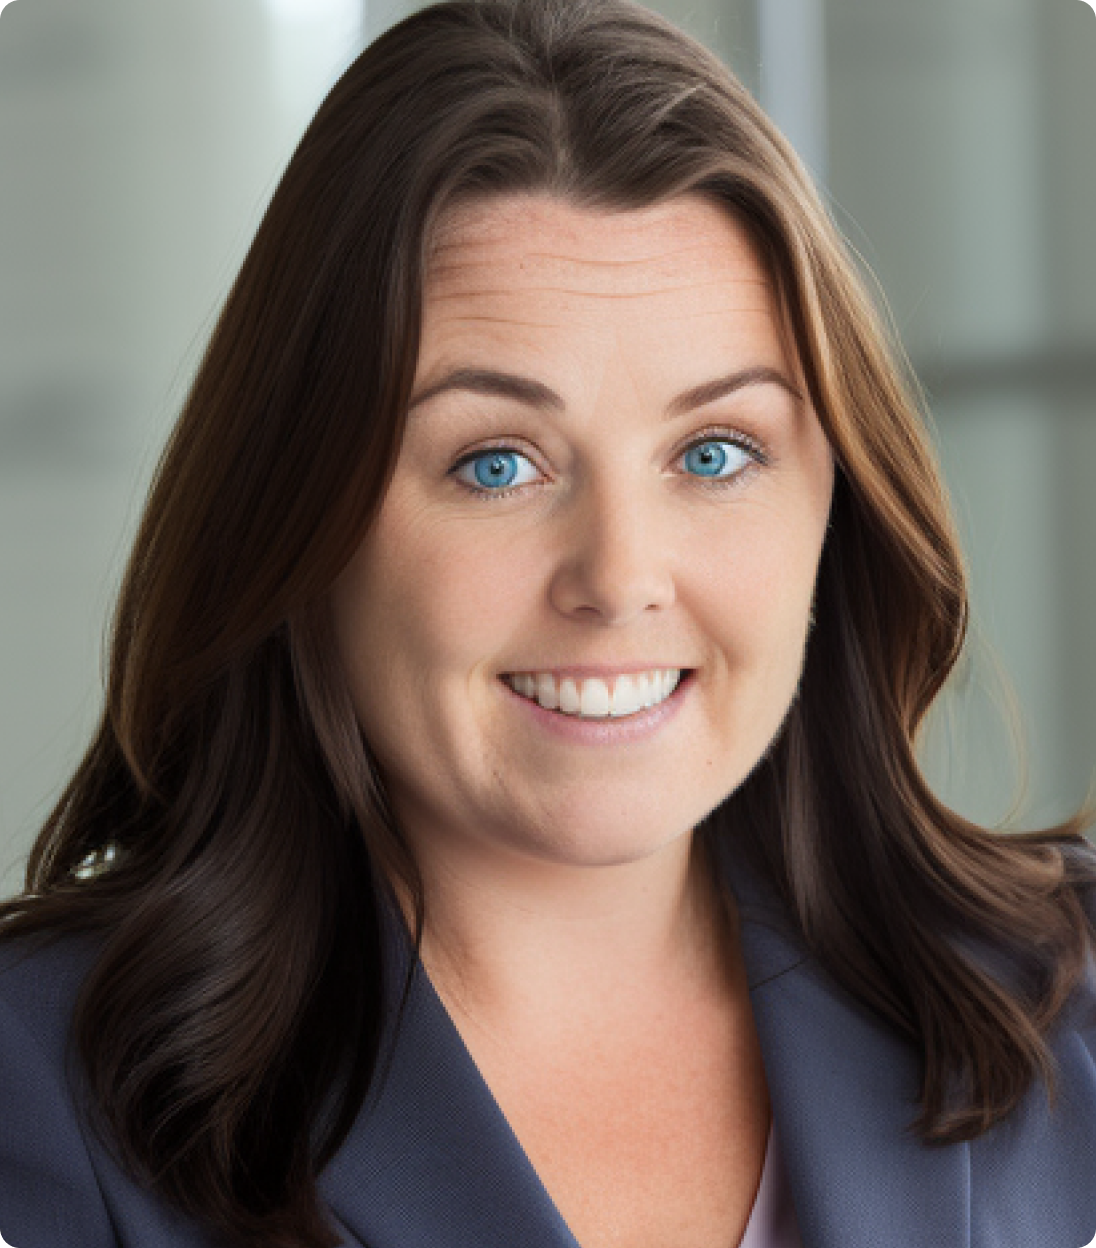
Elizabeth founded Kusmider Consulting with a simple goal: help people make informed insurance decisions without confusion or pressure.
As a Certified Financial Planner™, she brings a planning background to insurance work, focusing on how coverage fits into the broader financial picture, not just policy features.
If you’d like to discuss how a topic applies to your personal or professional situation, we’re happy to talk.
Schedule a Planning callLife insurance planning for people who want clarity, structure, and long-term oversight.
Securities offered through Simplicity Investments, Member FINRA/SIPC; 475 Springfield Ave, Summit, NJ 07901 (303) 797-9080. Kusmider Consulting is not affiliated with Simplicity Investments.
The Leaders Group, Inc. Customer Relationship Policy
Broker Check by FINRA .


