
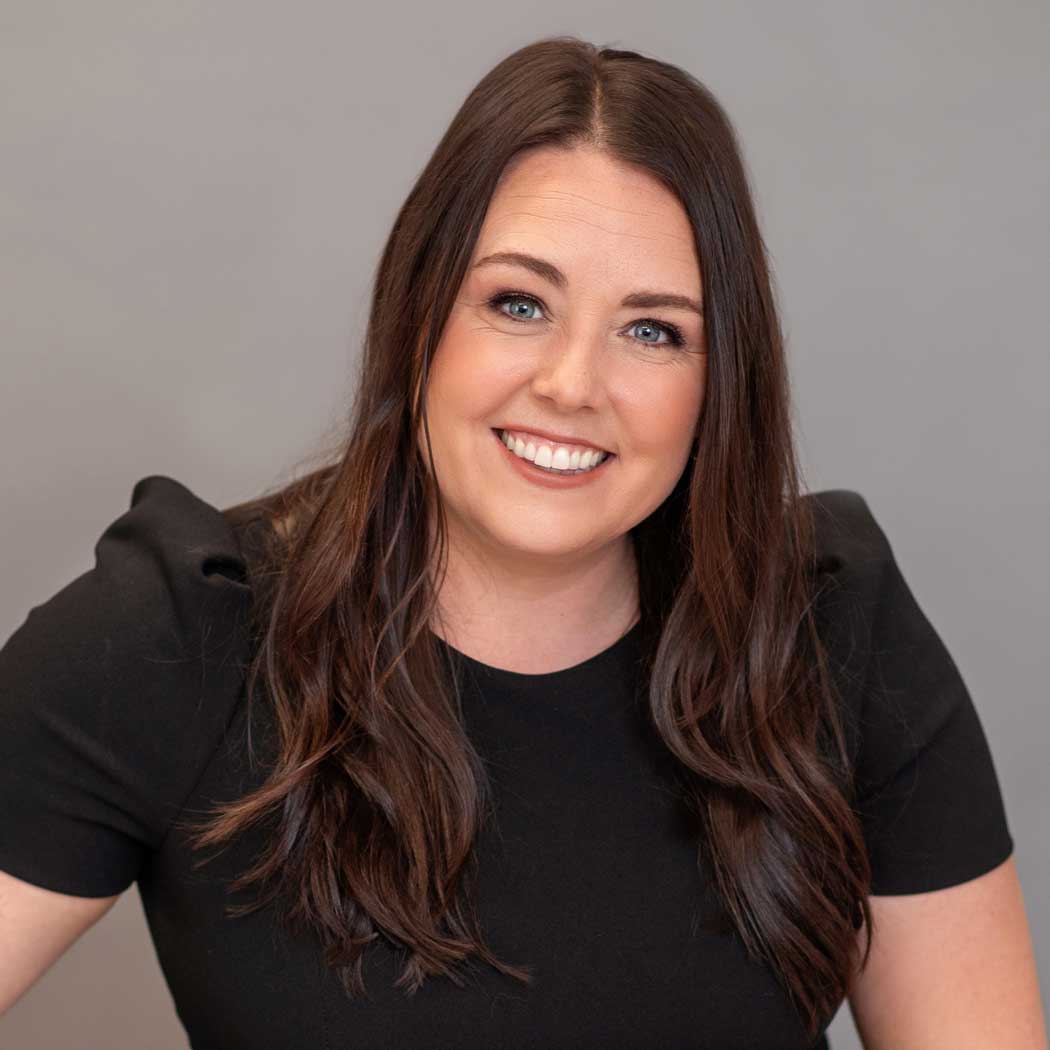
Elizabeth Kusmider, CFP®, helps you understand what care could cost, what Medicare will and won't cover, and how to fund care without putting your retirement at risk. No pressure, and no obligation to buy.
She helps individuals, couples and business owners plan for long-term care as part of their broader financial plan, working alongside CPAs, estate attorneys and wealth managers so your care plan, your coverage and your advisory team are on the same page.

Long-term care planning may be worth reviewing for:
Your care preferences first, products second.
Start With a Planning CallMedicare may cover certain skilled nursing or home health services when its rules are met, but not open-ended help with daily activities like bathing, dressing or supervision. A review shows where your gaps are.
Where you'd want care, who might help provide it, what care could cost, and what savings or coverage you already have.
Traditional and hybrid life-LTC options compared across carriers, side by side and in plain English.
Your care plan is coordinated with your retirement plan and the advisors you already work with.
Health changes can affect eligibility and pricing for private coverage, and starting early leaves more time to compare options and talk with your family.
Most families put off long-term care planning because they assume Medicare will cover it, the options are hard to compare, or they don't want to think about it yet. A planning call is built to address all three.
Any recommendation is yours to accept or decline.
We start with your care preferences, your family, and any coverage or savings you already have.
We look at what care could cost, what Medicare will and won't cover, and where your gaps are.
Funding options side by side, in plain English. You decide if and when to move forward.
We help implement the strategy and review coverage over time as your health, family, or retirement plans change.
There is no obligation to proceed beyond the initial conversation.
What it is:
A focused conversation to understand your situation, answer questions, and outline potential next steps.
What it is not:
A sales pitch or pressure-driven meeting.

Our role is to help you make confident, well-informed decisions over time.
A conversation about your care preferences, your family, and any coverage or savings you already have. You leave with a clearer picture, whether or not you move forward.
No. The call is about clarity. Any recommendation is yours to accept or decline.
Generally not for ongoing care. Medicare may cover certain skilled nursing or home health services when its rules are met, but not open-ended help with daily activities like bathing, dressing or supervision. A review shows where your gaps are.
Ideally while you're healthy. Health changes can affect eligibility and pricing for private coverage, and starting early leaves more time to compare options and talk with your family.
Yes. Elizabeth coordinates with your existing advisory team.
The goal of the first call is clarity about your care options, nothing more.
Start With a Planning CallLife insurance planning for people who want clarity, structure, and long-term oversight.
Securities offered through Simplicity Investments, Member FINRA/SIPC; 475 Springfield Ave, Summit, NJ 07901 (303) 797-9080. Kusmider Consulting is not affiliated with Simplicity Investments.
The Leaders Group, Inc. Customer Relationship Policy
Broker Check by FINRA .