

The best policy is not the one that sounds most sophisticated. It is the one that fits the reason coverage is being purchased.
Term and permanent policies often get compared as if one must be better. In practice, they answer different questions, and the confusion usually starts when the question has not been defined yet.
Before comparing premiums or features, it helps to name what the policy needs to do and for how long. The sections below walk through how each type fits that job.
Term life insurance is designed to cover a defined period of time. That can make sense when the need also has a defined timeline: raising children, paying a mortgage, replacing income during working years, or covering a business loan. The coverage is usually straightforward because the purpose is straightforward.
For many families, term coverage is the first practical layer of protection. It can provide a larger death benefit during the years when the financial exposure is highest.
Permanent life insurance is designed to remain in force as long as the policy requirements are met. It may be considered for estate planning, business planning, final expense planning, legacy goals, or situations where coverage is needed beyond a temporary period. Some policies also build cash value, though that feature needs to be understood carefully before it becomes part of the planning decision.

Permanent coverage is not automatically better because it lasts longer. It is better only when the long-term need is real and the funding commitment fits the client.
A family may buy a small permanent policy when what they really need is larger income replacement for twenty years. Another family may rely only on term coverage when they have a permanent estate or business need. Neither problem is about the product being bad. The issue is mismatch.
That is why the conversation should start with purpose: What should this policy do? How long does that need last? Who depends on the result? How does the premium fit into the broader financial plan?
The NAIC life insurance resources can help explain product categories, but the real decision should be made in context. Term and permanent coverage can also work together when different needs exist at the same time.
A practical plan may use term insurance for high temporary needs and permanent insurance for needs that do not go away. The policy type should be chosen after the job is clear, not before.
These help define the job the policy has to do before you compare products.
What happens when a term policy ends?
Coverage stops at the end of the term unless it is renewed, converted, or replaced. Renewal premiums are often much higher, which is why many people review their options well before the term ends.
Can I convert term life to permanent life later?
Many term policies include a conversion option for a limited time, but the rules vary by policy. Check the contract for the conversion deadline and the products it allows.
Does permanent life insurance always build cash value?
Not every permanent policy does. Some build cash value and some do not, and the cost, growth, and access rules differ. Ask for a clear illustration and understand the fees before relying on that feature.
If you have questions about your current coverage or want to understand how your policy fits into the broader picture, I am happy to walk through it with you. Reach out at info@kusmiderconsulting.com or call (713) 487-8855. The conversation is where it actually gets useful.
As a full-service, independent brokerage based in Houston, Texas and available throughout the U.S., we specialize in aligning insurance solutions with broader financial strategies. We provide expert guidance, unbiased product recommendations, and ongoing policy oversight to ensure your coverage evolves with your needs.
Whether you're reviewing your own protection or advising clients, we’re committed to helping you make informed, confident decisions.
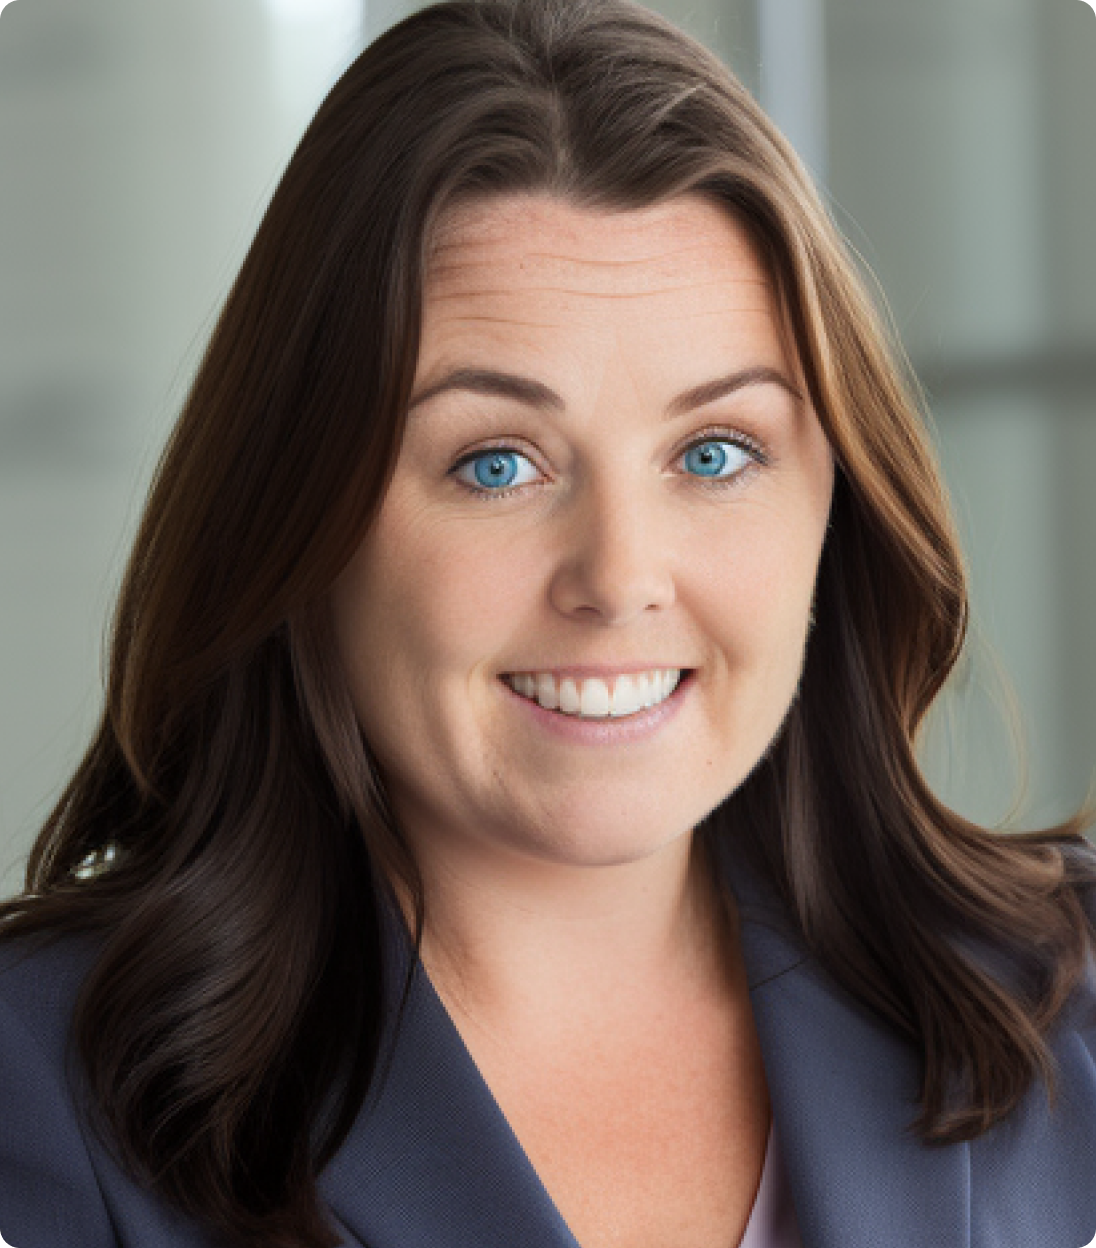
Elizabeth founded Kusmider Consulting with a simple goal: help people make informed insurance decisions without confusion or pressure.
As a Certified Financial Planner™, she brings a planning background to insurance work, focusing on how coverage fits into the broader financial picture, not just policy features.
If you’d like to discuss how a topic applies to your personal or professional situation, we’re happy to talk.
Schedule a Planning callLife insurance planning for people who want clarity, structure, and long-term oversight.
Securities offered through Simplicity Investments, Member FINRA/SIPC; 475 Springfield Ave, Summit, NJ 07901 (303) 797-9080. Kusmider Consulting is not affiliated with Simplicity Investments.
The Leaders Group, Inc. Customer Relationship Policy
Broker Check by FINRA .


